Investment Guide
AUD, USD, IDR: the three-currency problem in Bali property
By Ilia Siniak, Founder, Bali Family Development
29 July 2026 · 7 min read
Buy a villa in Ubud from Sydney or Perth and you are running three currencies at once. Almost nobody walks you through what that actually means for the money that lands in your account.
Three currencies, one investment
An Australian buying at Puri Sidem is not making one currency decision. They are making three, and they happen at different times over more than five decades.
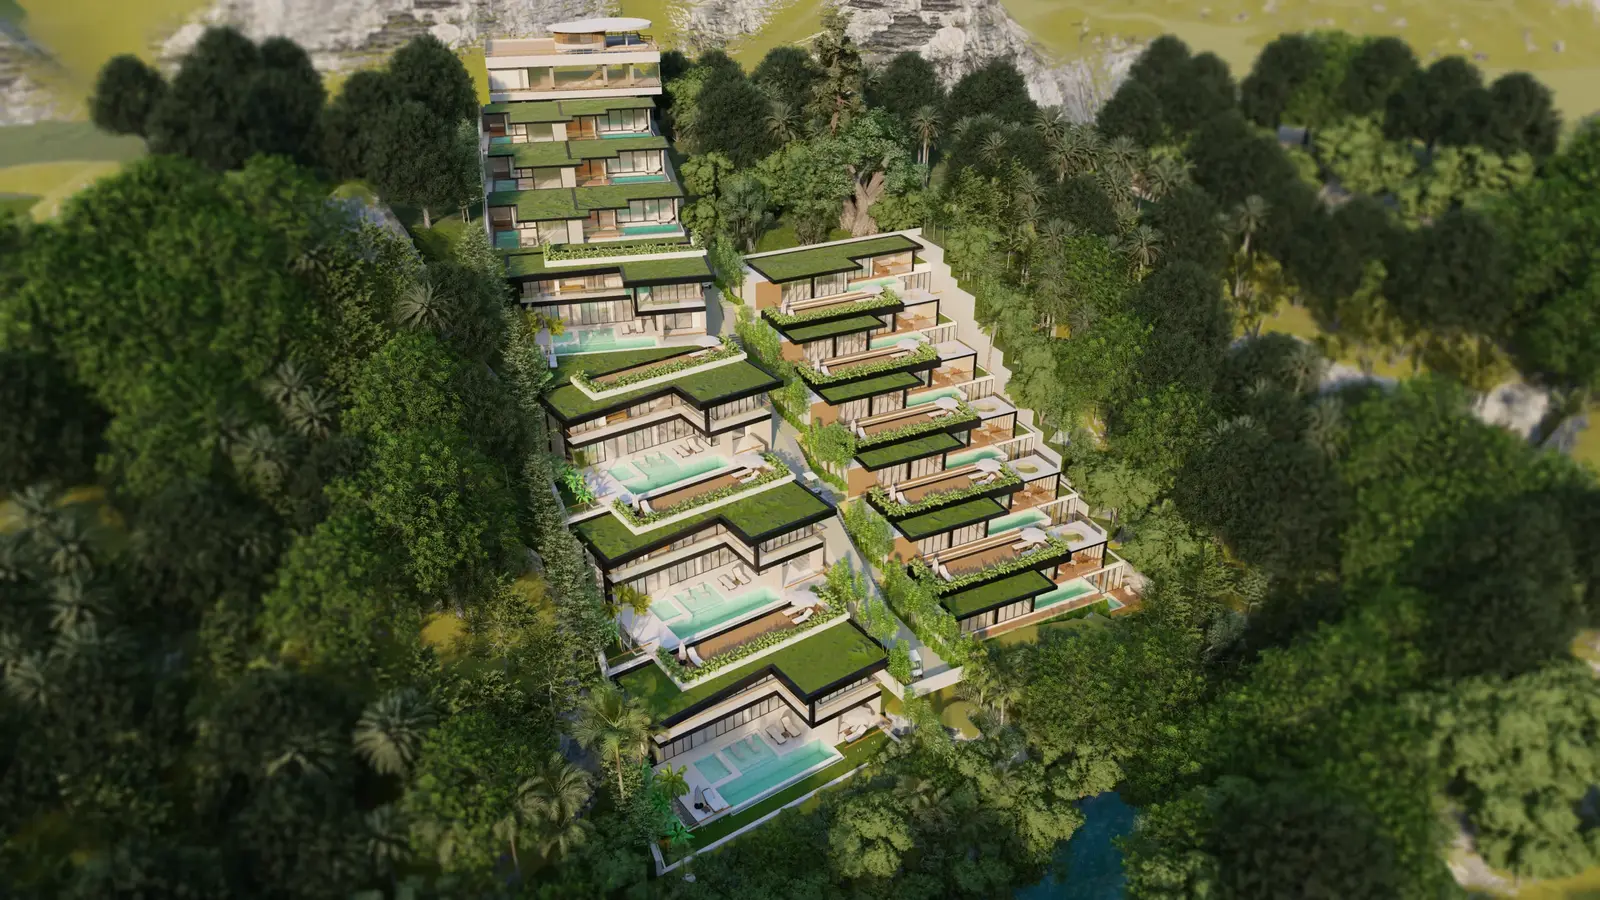
The purchase is priced in US dollars. The 16 residences on Jl. Bangkiang Sidem in Ubud, from the 103 m² one-bedroom to the 349 m² three-bedroom, are all quoted in USD.
The rent is collected in Indonesian rupiah, because the guest is standing in Bali paying an Indonesian operator. And your mortgage, your school fees, your grocery bill and your net worth are all measured in Australian dollars. Three currencies, three different points where value can be gained or lost, and none of them under your control.
What follows is mechanics, not forecasts. Nobody can tell you where the AUD will sit in Q3 2027. What you can do is understand where your exposure sits and decide, deliberately, how much of it to carry.
| Typology | m² |
|---|---|
| 1 bedroom | 103 |
| 2 bedrooms | 237 |
| 2 bedrooms | 252 |
| 3 bedrooms | 349 |
Leg one: AUD to USD, paid in instalments
Buying off the plan means paying in milestones between reservation and handover, which for Puri Sidem is July–September 2027. The contract price is fixed in USD. That is the part people misread as safety.
A fixed USD price does not mean a fixed AUD cost. Each time a milestone falls due, you convert Australian dollars into US dollars at whatever the rate happens to be that week. The USD number on the invoice never changes. The AUD number leaving your account changes constantly.
Take a single milestone payment. If the Australian dollar weakened against the greenback before that payment was due, the same USD amount would cost you materially more Australian dollars — for exactly the same villa. If the AUD instead strengthened, that milestone would cost less. Nothing about the property changed. Only the exchange rate did.
Multiply that across every remaining instalment and the swing is material. The guaranteed lease extension — 25 additional years for 15% of the purchase price — is one more payment in the same currency, decades away.
Leg two: the rent arrives in rupiah
Once the villa is operating, the money starts in IDR. Guests pay an Indonesian operator, operating costs are paid locally in rupiah, and what is left is the net figure your distributions are calculated from. The underlying asset lives in an Indonesian ledger.
The single most important question to settle before you sign is which currency your distributions are actually denominated in. Distributions contracted and paid in USD mean the operator absorbs the IDR-to-USD movement. Distributions calculated in IDR and simply converted for your benefit mean you absorb it. These are two very different products wearing the same headline number, and the difference will not be obvious from a brochure.
Then comes a second conversion. Money reaching an Australian resident has to become AUD eventually, so you are running IDR to USD to AUD, and each hop carries a spread and often a fixed fee. Distribution frequency matters too: quarterly payments mean four conversion events a year rather than one, spreading your rate risk but multiplying transaction costs.
Leg three: the exit, and the tax office
Leasehold property in Bali is generally resold to another foreign buyer, and generally priced in USD, on whatever term remains of the 27-year lease plus the 25-year extension. So the exit is one more conversion, usually the largest single one.
Capital growth in USD is not capital growth in AUD. Sell for twenty per cent more USD than you paid, and if the Australian dollar has strengthened by a similar amount over the same period, you land back where you started in the currency you actually spend. The reverse is equally true and equally out of your hands.
There is an Australian tax layer on top. The ATO deals in Australian dollars, so foreign gains and losses are translated into AUD using the relevant rates, and rent received is reportable in AUD too. This means an exchange rate movement can affect your assessable position even where the USD figures look flat. Capital gains tax treatment of a foreign leasehold interest is not something to work out from a website — including a blog post — so get it in writing from an Australian tax adviser before you commit, not after settlement.
Practical ways Australians manage the exposure
The realistic goal is not to eliminate currency risk — you cannot, if you hold an offshore asset — but to stop it all landing on a single day. A few general approaches are worth understanding.
Stage your conversions. An off the plan purchase with milestones spread to Q3 2027 is already a natural schedule; converting a portion at each stage, rather than one lump sum, averages out your entry rate instead of betting everything on one morning's price.
Understand forward contracts. A forward lets you agree today on a rate for a conversion on a future date, which turns an unknown AUD cost into a known one. They are commonly arranged through banks and specialist foreign exchange brokers. They also carry obligations — typically an upfront margin, a top-up requirement if the market moves against you, and a binding commitment to settle even if the spot rate ends up more favourable. If you go down this path, deal only with a provider holding an Australian financial services licence and read the product disclosure statement properly.
Consider holding a portion in the asset's currency. A USD account lets you convert when you choose rather than when a milestone forces your hand, and if you intend to reinvest rent received offshore or spend time in Bali, converting to AUD and back again just pays two spreads for nothing. Finally, compare the total cost of a transfer — spread plus fees — rather than the advertised rate, and keep an AUD buffer so an adverse move never forces a rushed conversion at a bad moment.
The questions to ask before you sign
Currency risk is mostly managed with paperwork. Get clear written answers to these before contracts are exchanged.
Which currency is the purchase price denominated in, and does the contract contain any exchange rate adjustment clause? Are distributions calculated and paid in USD or in IDR, and who wears the conversion between them? What reference rate and what date are used for each conversion, and is the applied spread disclosed? How often are distributions paid, through what banking channel, and what Indonesian reporting or withholding applies before the money leaves? And in which currency, and on what basis, is the 15% lease extension payment calculated when it falls due?
A developer running a serious project should answer all of these without hesitation. Vague answers are information in themselves.
General information only
This article is general information about how currency exposure works in an offshore property purchase. It is not financial advice, foreign exchange advice, tax advice or a recommendation to buy any product or to use any particular provider, and it does not take account of your objectives, financial situation or needs.
All exchange rates used here are indicative and for illustration only; rates move continuously and the figures shown are arithmetic on hypothetical scenarios, not forecasts. Before acting, speak with a licensed Australian financial adviser and a tax adviser familiar with foreign property interests, and read any product disclosure statement in full.
Questions about your own situation?
Tell us what you are weighing up and we will come back with the detail you need: legal structure, timelines and which units are still available.
More guides
Investment Guide
Buying Off the Plan in Bali vs Off the Plan in Australia
Most Australian buyers already understand off the plan. The trap is assuming the protections that come standard in Sydney or Brisbane also come standard in Ubud. They do not, and knowing exactly which ones are missing is the whole job.
Investment Guide
Can an Australian SMSF hold overseas property? What to understand first
It is one of the most common questions Australians ask about offshore property, and one of the easiest to get wrong. Here is the factual groundwork — the concepts, the sticking points, and the questions to take to a licensed adviser.
Investment Guide
Rent earned overseas and the ATO: what Australian investors need to understand
Rent earned overseas is not invisible to the ATO. A plain-language map of the concepts behind rent earned overseas, and the questions to take to a registered tax agent.